I invested £157k at 27 – so when I hit my 40s work can be just an option
‘I don’t want to retire – I want to be work optional’
Welcome to In This Economy? An all-too-real series by The Tab, looking into the bleak money and job market young people in the UK are facing. A comfortable bank balance and no worries? Not in this economy.
A 27-year-old has revealed how she already has £157k in investments, so work can be “optional” come the time she’s in her 40s. Ankita Kaur had been investing sporadically by learning from people online, before she got her first time role in consultancy a year later.
It started when Ankita was paying into a workplace pension, and when her salary surpassed £50k (maybe the first hurdle for making this not doable for most), meaning she fell into a higher tax bracket, Ankita started increasing her pension contributions to reduce her tax.
She then discovered a movement called FIRE movement – financial independence, retire early. Honestly, isn’t this just what we all want in life? One of the main plans in the movement is to build a pension pot early.
She has now claimed she is earning nearly six figures, and contributes over half of her salary into her workplace pension. In four years this has grown to £126k, due to her large contributions from her and her employer and investment growth.
Ankita also has £25k invested in a stocks and shares ISA, and £6k in a general investment account invested in individual stocks and ETFs. Casually.
via SWNS
“I don’t want to retire – I want to be work optional,” she said. “I want the freedom to know if I was stuck in a bad job, I could walk away from the situation. It doesn’t mean I’m trapped.”
Ankita started investing in 2021, after seeing online about how it can “make you rich”. Working as a private tutor she would typically invest a few hundred pounds each month sporadically into a general investment account to look after her financial future.
“Once my salary got past £50k, I was going into the higher tax bracket,” she explained. “I was speaking to my husband and we realised if I contribute more into my pension, I won’t need to pay 40 per cent tax. I also invest whatever I have left at the end of each month, into a stocks and shares ISA.”
She added: “I think I always knew putting money into a pension was a good idea. I saw the headlines saying ‘I retired at 30’, and I was curious about how it was possible. People would put out their stories on Reddit and YouTube about how they were investing heavily so they could retire between 30 and 45. I started reading a lot, seeing what people’s experiences were.”
As Ankita got more confident with her investing skills, she started to make what even she admits are “riskier investments” based on what she learnt through reading online.
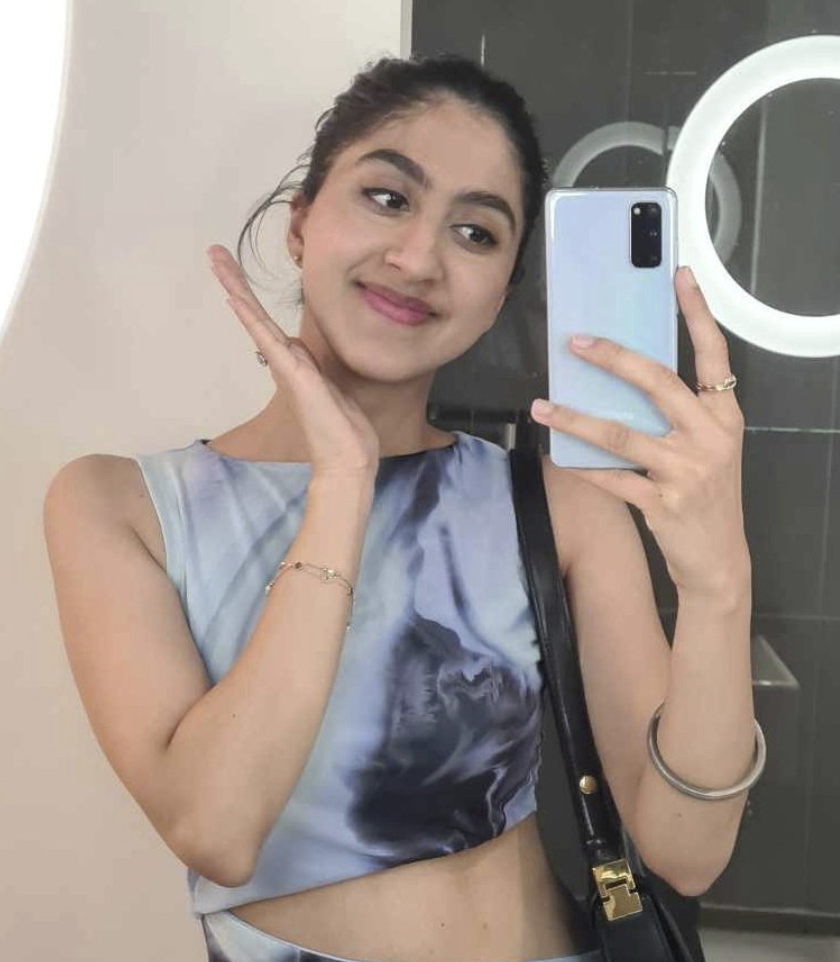
via SWNS
She currently has £157k invested in total, and said if you assume a real return rate of five per cent, she’ll have £296k by the time she is 40. This will rise to £781k by the time she’s 60.
Ankita will not be able to access her pension until she is 55 at the earliest, so she plans to work on bridging the gap by saving more into her ISA to financially support herself between her forties and pension access age.
“The early access age for my pension is set at 55,” she said. “I calculated by the time I get there, the access age will probably be closer to 60. Before I was pretty sure I was going to keep contributing into my pension, but I did the maths and realised, with FIRE, I can stop contributing as much.
“I will now be matching my employer’s contribution and instead put more into my Stocks and Shares ISA. I’m now building the bridge to tide me over until I can access my pension.”
Ankita is aiming to be work optional by 40, but is likely to continue to work on her own terms to become financially free. “I’m trying to build more sources of income so I can reach this goal earlier,” she said.
For more, like The Tab on Facebook. Pictures and story via SWNS.
Latest
The future of The Pitt is sketchier than ever as judge rules ER lawsuit can proceed

Well, it had a good run
Fights, fainting, and freak-outs: The unaired Celebrity Traitors moments the BBC kept from us
Dear BBC, please email me all the raw footage
Opening soon! Three new food spots coming to Cambridge this winter
Burgers. Brunch. Sushi. The food scene in Cambridge just keeps getting better

20-year-old University of Arts London student dies after being rejected by love interest

Junmo Jeong mother said he was ‘not isolated, nor was he disengaged from life’
Hear him out: Traitors winner Sebastian Croft reckons he knows why Maya flew under the radar, and it’s genius
I need Maya to comment like now
James Blunt is still defending his Celebrity Traitors castmates in the most unexpected way

Someone give him some media training
MAFS UK has been axed, but the scandals that plagued the show have been going on for years

This decision should have come sooner

The Celebrity Traitors’ Kenny made plan with Maya to banish her at the final roundtable

She knew he was going to throw her under the bus
Ouch, Joanne McNally is in trouble with the BBC after ‘juicy’ Celebrity Traitors podcast episode
‘We’d be taken to the gallows’
Channel 4 confirms MAFS UK ‘will not return’ as external review concludes after assault claims
The show has been cancelled for good
How Christa Pike’s fate might now have been sealed by the US midterm elections
The new governor has strong opinions

The Love Is Blind US S11 cast already on Cameo, and how much they charge

Benita from the pods charges £499.93
Three huge bombshells that are set to come out at the Love Is Blind season 11 reunion
A lot has happened since filming ended
Love Is Blind’s Erika and Blake broke up after ‘direct conversations’ about ‘finances’
‘The math wasn’t really mathing’
Former cast member breaks down exactly how couples plan their weddings on Love Is Blind
She’s clarified exactly how much input they have
Things to do when you have a friend visiting York

Why not share the love of York and be the ultimate tour guide